Latest News & Resources

Articles, sessions, and practical guidance based on real deal flow, real operators, and real constraints.

This hub exists to explain how deals work in practice, not how they’re supposed to work on slides.
Everything here is written or reviewed by people who actively participate in the ecosystem and something you rarely find somewhere else.

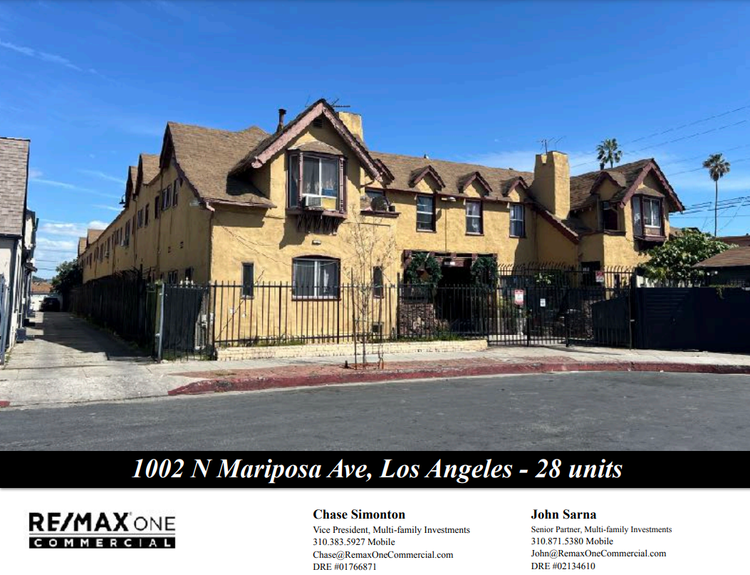
1002 N Mariposa Ave
Offering Price: $4.8M

  • 28 Units in Hollywood California
  • Current NOI: $263,275
  • Pro Forma NOI: $521,342

SRO in
San Francisco

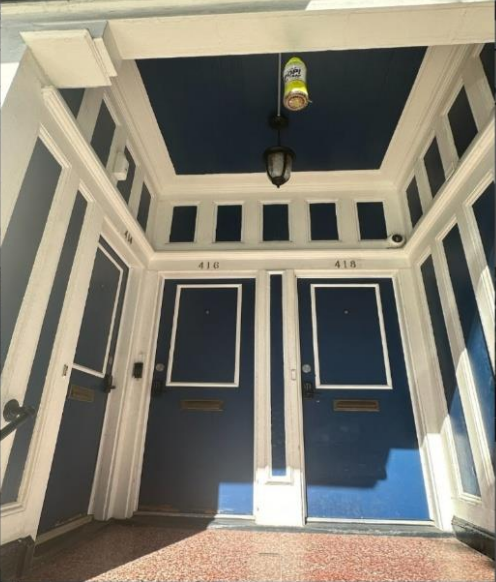
15-unit SRO building offering a potential gross annual income exceeding $225,000 located in the thriving SoMa neighborhood of San Francisco. Asking price: $3.2 million.
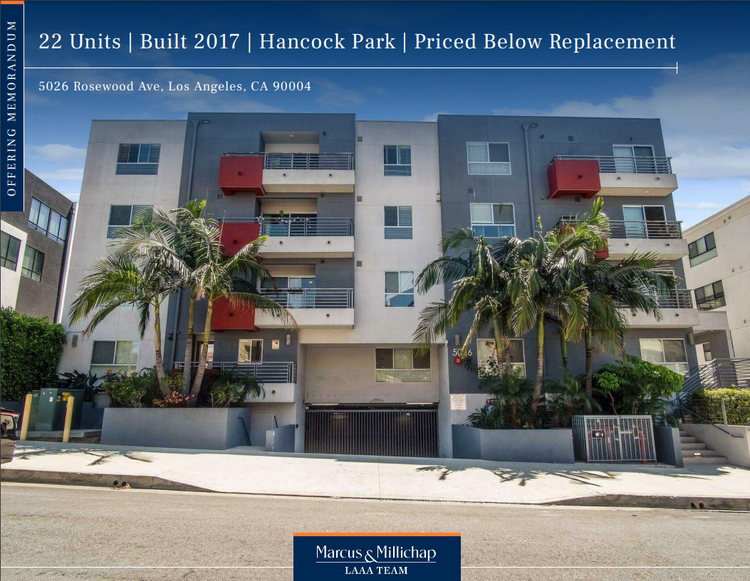
Rosewood Ave
Offering Price: $11.4M

2-unit multifamily property located at 5026 Rosewood Ave, Los Angeles, CA 90004.
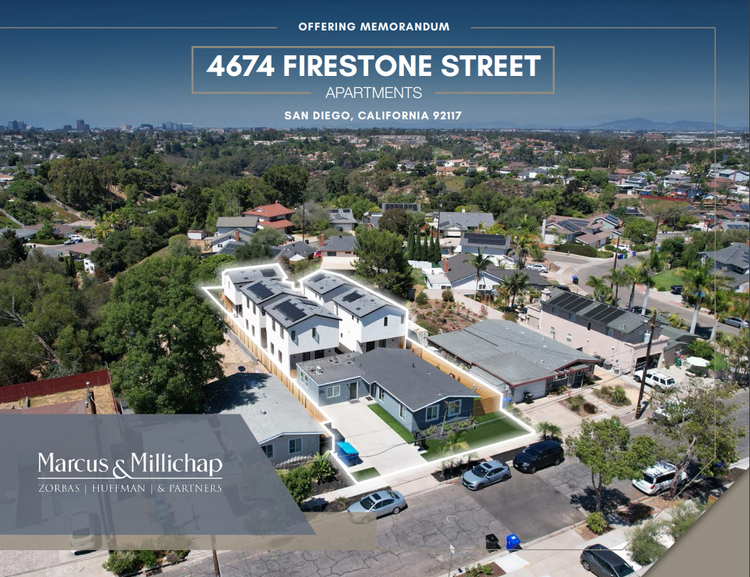
Firestone | Multifamily,
San Diego Offering Price: $5.53M

A newly constructed pride of ownership asset in the desirable Clairemont neighborhood of San Diego, CA.

The asset features a combination of brand new, detached townhome style construction with contemporary design, behind two luxurious and fully renovated street facing units.

The property boasts a unit-mix of one (1) three-bedroom / two-bathroom single family residence with 953 square feet, one (1) one-bedroom/one-bathroom unit with 375 square feet, and ten (10) newly constructed one-bedroom/one-bathroom units with 441 square feet. The single-story units have undergone extensive luxury renovations, with no expenses spared, and the finished product of the newly constructed units is superior in kind and most important to quality.

– Current NOI: $262,249

– Pro Forma: $280,288
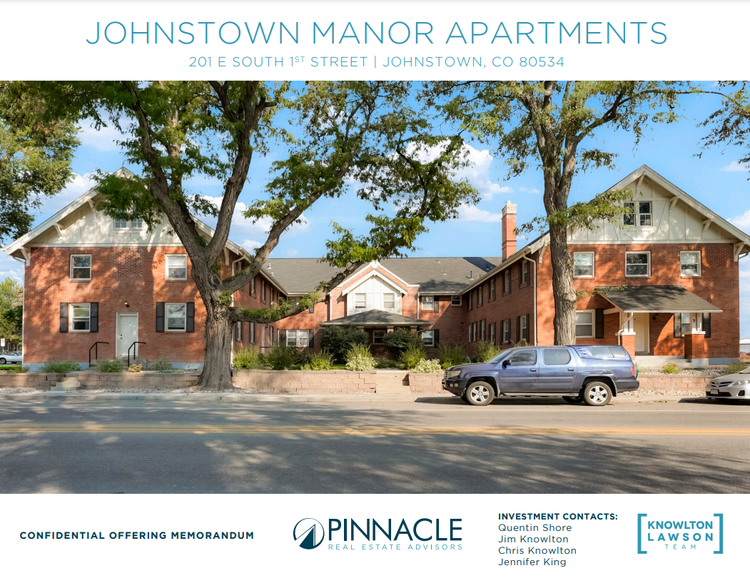
Johnstown Manor Apartments 
$2.4M

201 E. South 1st Street is a 13-unit apartment building located in Johnstown, CO. These units feature a unique mix consisting of (4) 1Br/1Ba units, (6) 2Br/1Ba units, and (3) 3Br/1Ba units. This turn-key investment is in excellent condition and requires little to no capital injection.

Current ownership has updated the majority of the electrical panels in the units (2021), installed a new roof and gutters (2017), and recently installed a new boiler. With a history of strong occupancy rates and stable rental income, the property is poised to continue generating consistent cash flow.

– Current NOI: $136,945

– Pro Forma NOI: $157,859
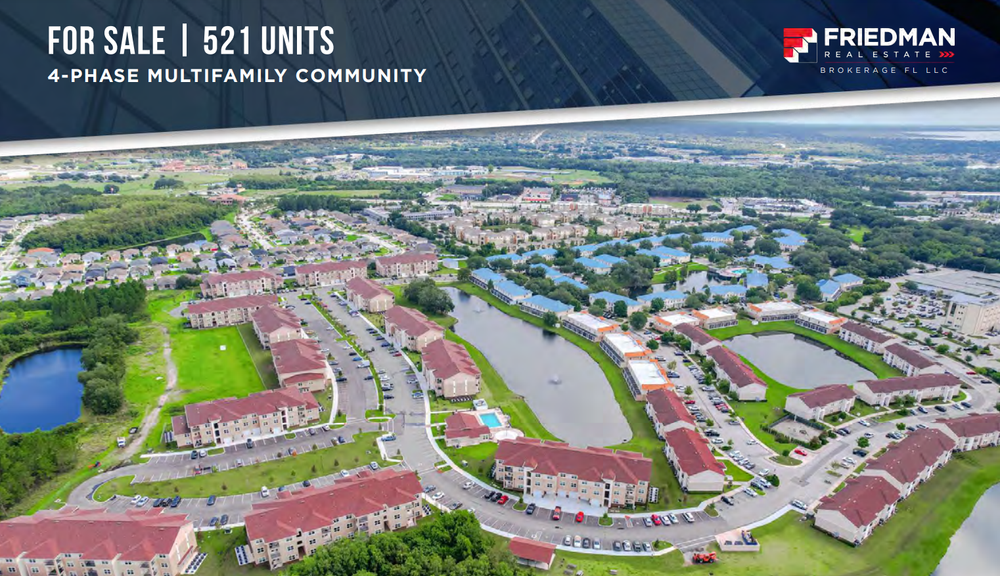
Heritage
Key Villas

Newly constructed 4-phase multi-family community located in Kissimmee, Florida. 521-units completed 2024 with additional undeveloped +12.11 acres of land adjacent with potential to add up to 250 additional units included. Located immediately southeast of NeoCity Research and Technology Campus. Situated at the center of Orlando International Airport, Disney World, HCA Florida Hospital, and a plethora of retail amenities. Property is offered free and clear of existing financing however; it can be purchased with a combination of new financing along with assuming attractive below market agency debt on phases II and III. Please inquire for details.
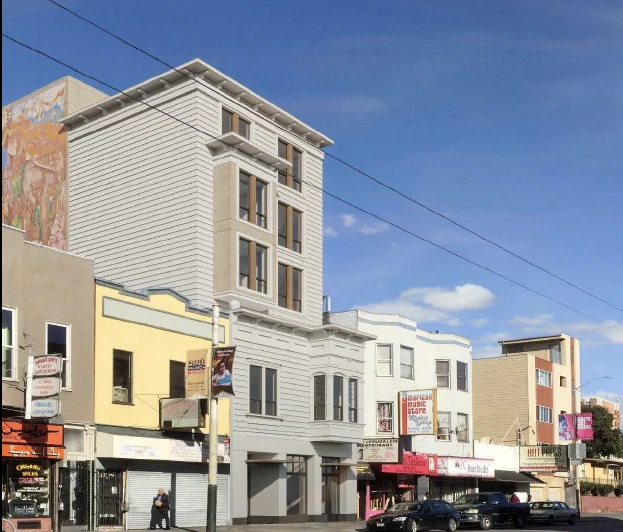
Opportunity to Build a Mixed-Use, 8 Condominiums and 1 Commercial unit in the Vibrant Mission/Noe Valley/Bernal corridor of San Francisco | Offering Price: $1.875

Opportunity to build a fully entitled mixed-use development in the vibrant Mission/Noe Valley/Bernal corridor. Plans include an elevator building with 8 condos (seven 2BD, one 1BD), bike storage, and 1 ground-floor commercial space, totaling 11,956 sq ft.

Located near 24th Street BART, SF General Hospital, and top restaurants, this A+ location offers excellent commuter access. Median area salaries exceed $166k/year, with 20% growth expected, aligning with demand for modern, efficient living.

Corporate bus stops for Google, Apple, and others are nearby, and SFO is just 20 minutes away. Build and sell or lease this incredible opportunity today!
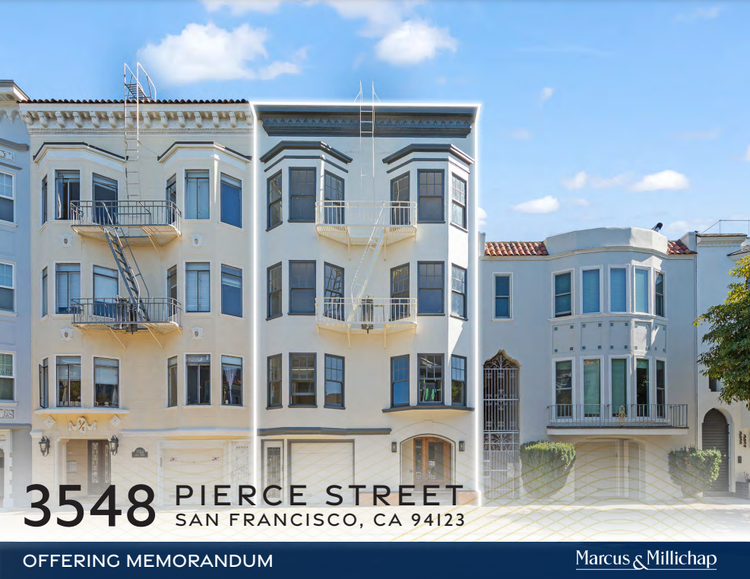
3548 Pierce Street,
San Francisco CA

Welcome to 3548 Pierce Street, a newly renovated multifamily gem in San Francisco. This six-unit building features two 1-bedroom and four 2-bedroom luxury units, all upgraded to condo-quality standards.

– The property offers ADU potential with cleared garage spaces and boasts premium updates like a new heating system, intercom, water heaters, and a stylishly renovated lobby. Located in a prime area with a 97 Walk Score, it’s steps from shopping, dining, and entertainment.

– Perfect for investors or multigenerational living, this property blends modern upgrades, pristine condition, and an unbeatable location. A rare opportunity not to be missed!

– Current NOI: $221,144

– Pro Forma NOI: $258,584
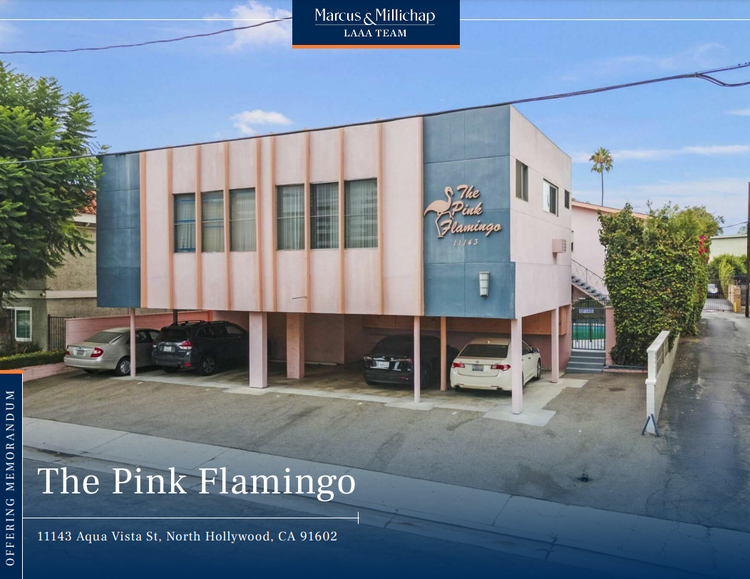
Aqua Vista
Offering Price: $2.6M

10-unit multifamily property located at 11143 Aqua Vista Street in the highly desirable Studio City neighborhood.

– This property is subject to LA City’s Rent Control (RSO), and this is the first time the property has been listed for sale in over 35 years.

– The property spans 6,895 square feet on a lot of 8,531 square feet and includes on-site amenities such as a pool, laundry facilities, parking, and air conditioning in most units.

– Current NOI: $113,185

– Pro Forma: $174,063
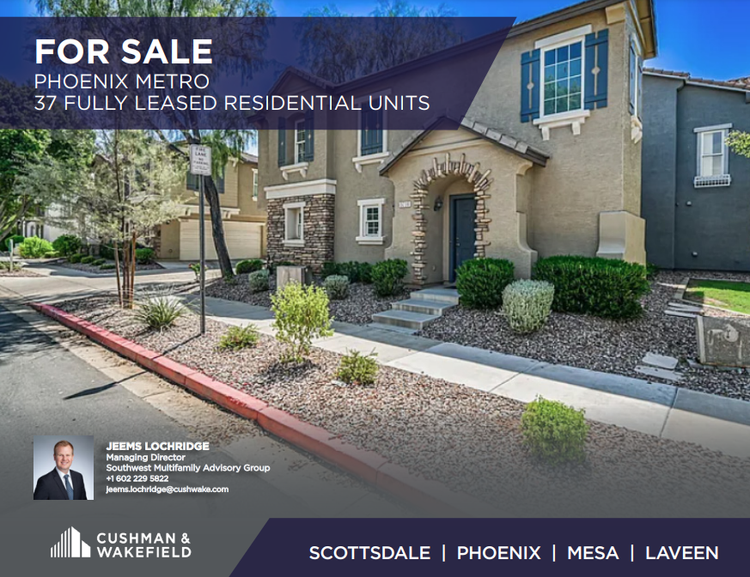
Phoenix Metro 
37 Residential Units

Cushman & Wakefield, U.S. Inc. is pleased to announce the exclusive listing of 37 Fully Leased Residential Units located in the Phoenix MSA. The Phoenix Metro area is a proven market for residential rentals with more homes purchased by real estate investors than any other U.S. city.

This Phoenix Metro 37 Portfolio provides an investor to build scale quickly in the Phoenix Market at a very attractive basis. All of the units are individually parceled, providing exit flexibility through a retail disposition.

– Pro Forma NOI: $477,024
Villas at
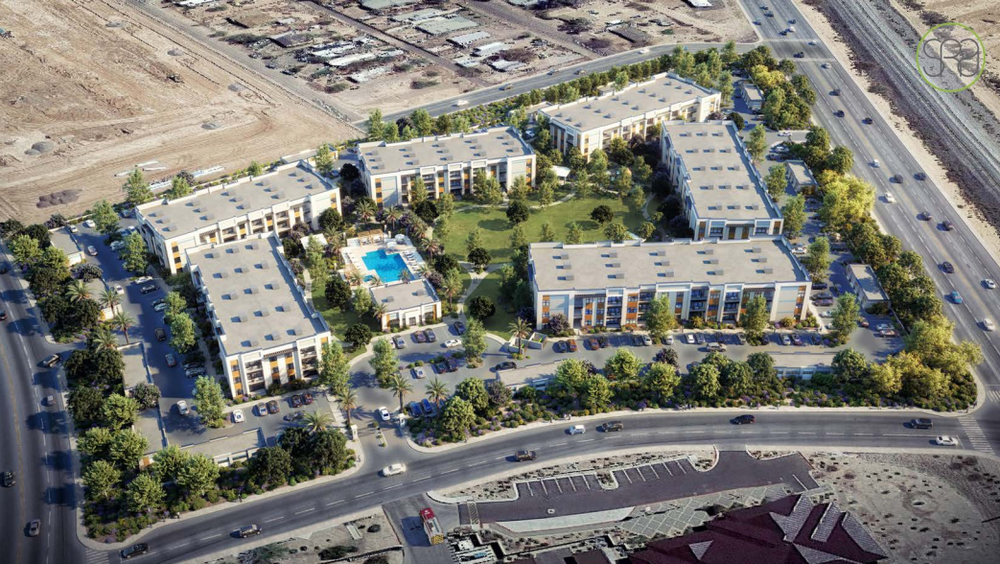
The Gin

Completed rezoning and nearly fully approved construction drawings for a 195 unit garden style apartment complex development with 70+ garages, a pool, pet amenities, and a clubhouse.

Max density 20 units/acre, proposed density 19.17 units/acre. 78, 1 bedroom units, 99, 2 bedroom units, and 18, 3 bedroom units. 14 garage buildings with 5 spaces per building for 70 rentable garage spaces, 399 total parking spaces.

This project is nearly ready to come out of the ground for the right buyer.
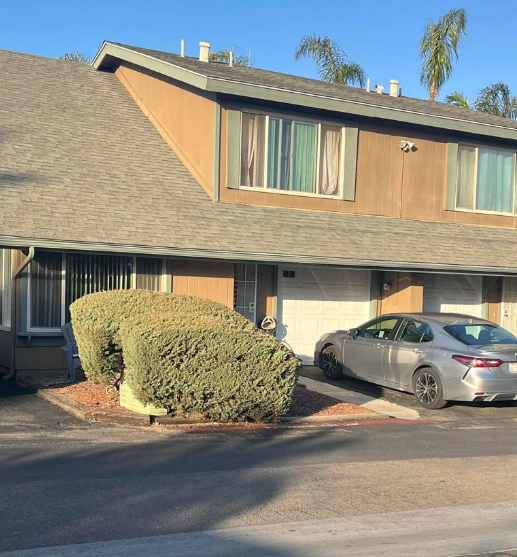
Excellent Opportunity Large 3-bed, 2-bath Vista, CA

Opportunity Knocks! Excellent investment option just a short drive from revitalized Downtown Vista. Keep current long term tenant or put in some TLC update with paint and flooring & hold it as a long-term rental, or enjoy it as your primary property.

Large 3-bed, 2-bath unit spread across two levels. Entry on the ground floor. Nestled in the quiet Citrus Grove gated community with only 28 units, residents enjoy access to pool & landscaped grounds.

FHA or VA financing possible! Short drive to the beach & everywhere you want to be in North County!
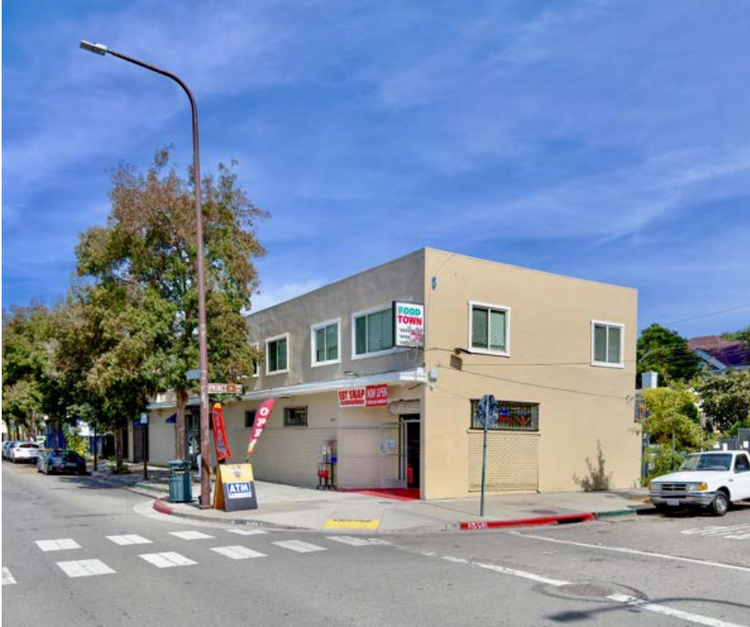
13-unit Mixed-Use Building
Berkeley, CA

PROPERTY HIGHLIGHTS:
Retail spaces are fully occupied with
excellent frontage on Sacramento Street
• Fully leased property with a steady
revenue stream from a diverse unit mix
• Gated Parking
• Two buildings, including a detached home
• Excellent street visibility along
Sacramento Street
• Easy Access less than a mile from BART and multiple freeways
• Commercial Zoning
– Current NOI: $205,274
– Pro Forma NOI: $224,043
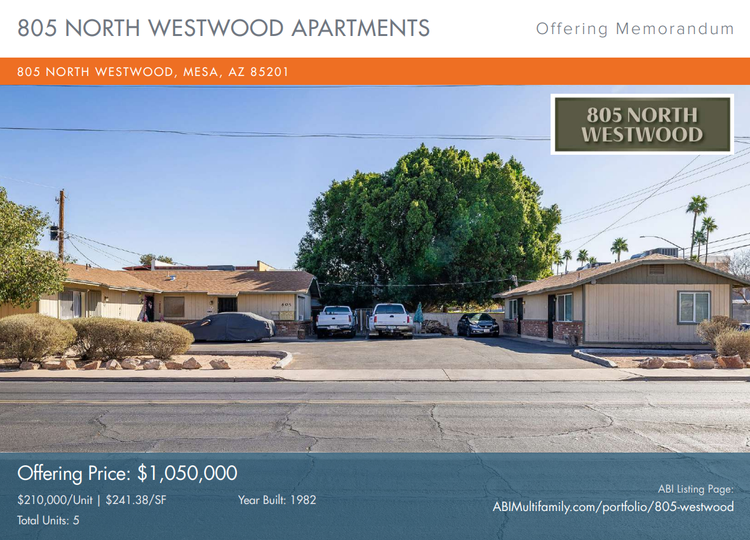
805 N Westwood, Mesa, AZ 85201 | Offering Price: $1.05M

5-unit multifamily deal in a nice, quiet pocket of Mesa, Arizona. The offering includes a duplex and triplex, each on their own tax parcel (option for residential or commercial financing) with a shared parking lot between them.

(4) 2/1.5s and (1) 2/1. 80s build.

Long-term strong tenants. Both units in the duplex have recently been fully remodeled, and all three units in the triplex are unrenovated but in great condition.
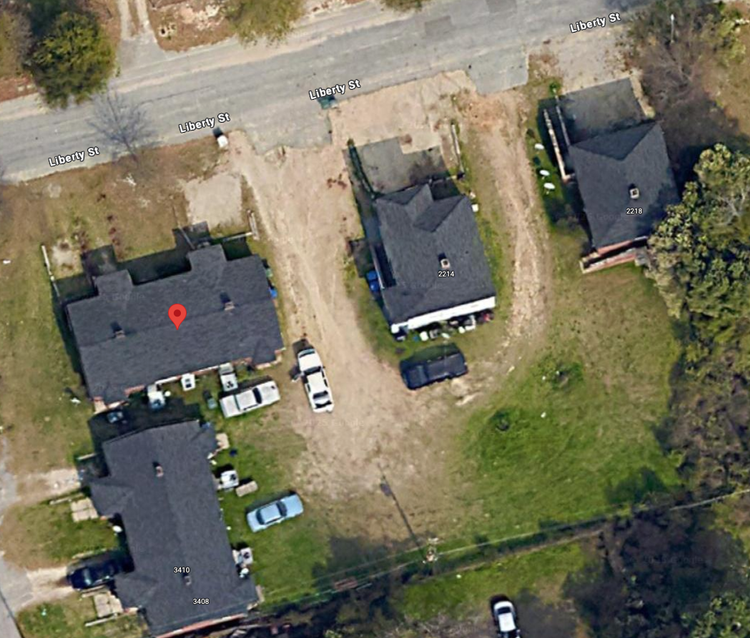
4 duplexes on the same block in Columbia, SC Offering Price: $920,000

Great opportunity to get a cashflow from day 1
– conveniently located in the up and coming area and 10 minutes from downtown, university, shopping centers, etc
– recently renovated
– 7 units out of 8 are tenant occupied (may be fully rented very soon)
– property management is in place
– current gross rent is $7,825.
– potential to get one more tenant and increase rents with pro-forma close to $9,500-$10,000
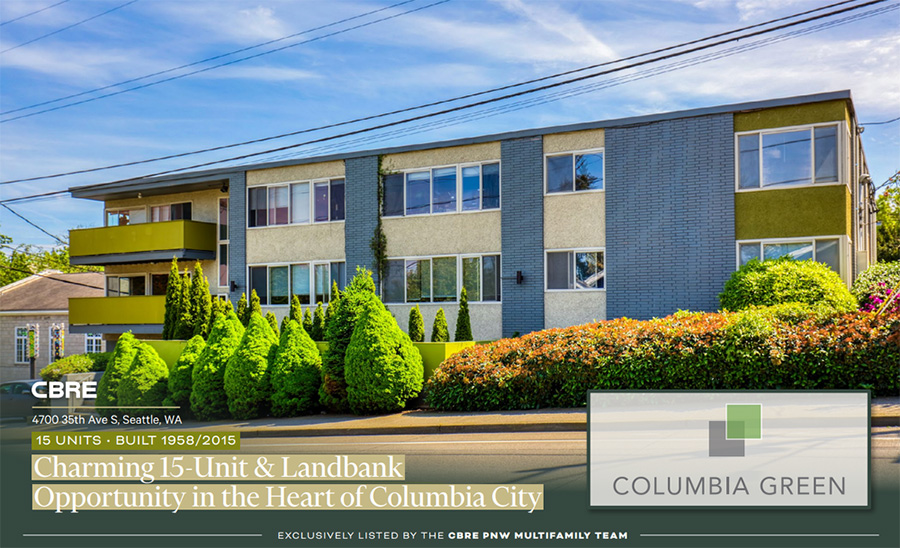
Columbia Green
Apartments

This 15-unit apartment complex is centrally located in Seattle’s thriving Columbia City neighborhood. It was renovated in 2015 and sits on a large corner lot. Rents are growing quickly, and occupancy is steady. Ideal candidate for a 1031 exchange! Close to employment, shops, dining and recreation! Don’t miss out on this opportunity.

– Current NOI: $250,088

– Pro Forma NOI: $290,449
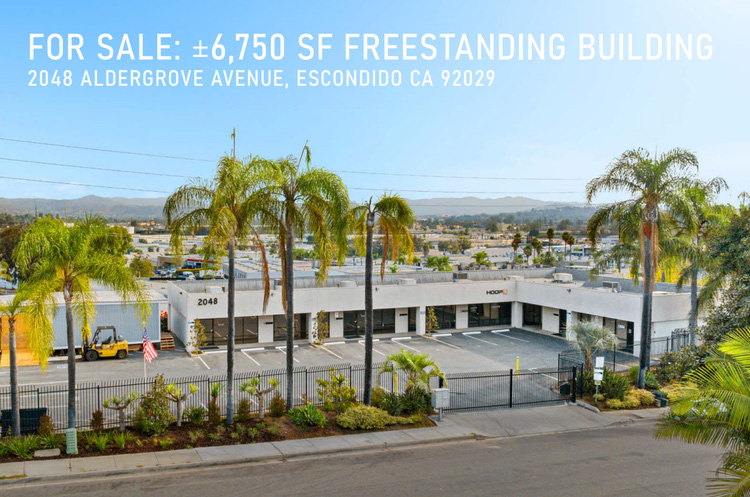
Multi Tenant Flex Park $325/sf – Escondido CA

Excellent Multi-Tenant Flex park for sale in Escondido CA. 8 total units equaling 6,750sf. Units ABC will be delivered Vacant. Units DEF are leasing until Sep 30 2026 but would like to sign an extension now. Units GH are month to month but want to stay. All Income is under market at $5,150/mo.
The Wesley Apartments

The Wesley – 67 units

Imagine securing your future with a robust “property investment” in the heart of Dallas. Our latest “commercial real estate investing” opportunity, Wesley, offers projected returns of 16% IRR and nearly 2X equity in 5 years, leveraging the high-demand “dallas real estate” market to generate significant “passive income” and pave your way to “financial freedom”.
Off-Market Deal — Stone View on McQueen

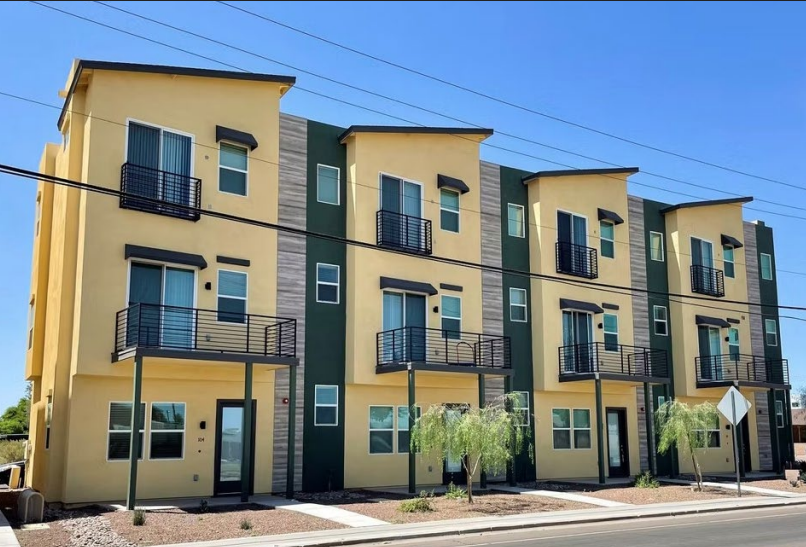
This is an off-market opportunity to acquire Stone View on Horne, a 10-unit Class A townhome property. This 100% leased turnkey investment was built in 2023 and is in excellent condition. All of the units are 4-bedroom and 3.5 bathrooms with a private attached garage.

The spacious units offer 2,200 square feet and are all 3-stories. The dwellings offer stainless steel appliances, quartz countertops, custom cabinetry with kitchen island, plank flooring, walk-in closets, ceiling fans and in-suite washer and dryer.

The property is conveniently located within walking distance to Downtown Mesa and the light rail. It is in proximity to parks, retail, freeways and major employers. It’s location across the street from the 28.29 acre Eagles Park offers an additional recreational amenity for residents.
Off-Market Deal — Stone View on McQueen

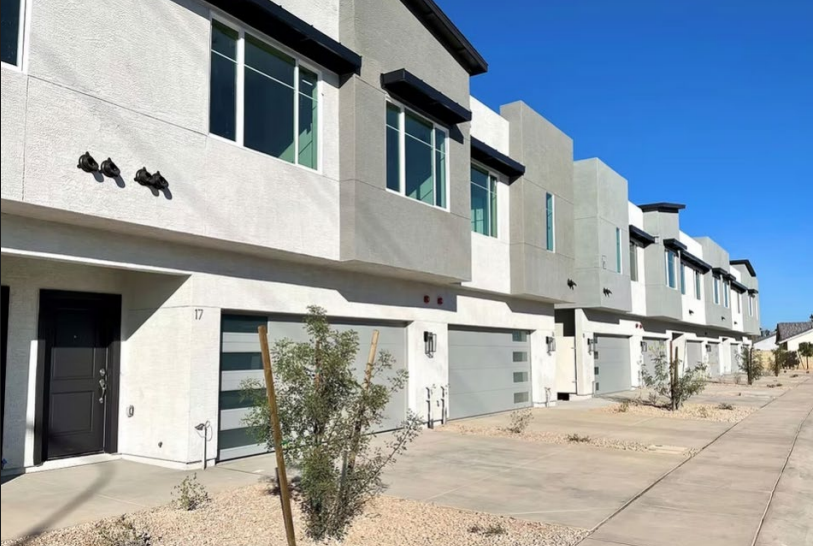
This is an off-market opportunity to acquire Stone View on McQueen, a 19-unit Class A townhome property. This 100% leased turnkey investment was built in 2022 and is in excellent condition. All of the units are 3-bedroom and 2.5 bathrooms with a two-car direct access garage.

The spacious units average 1,795 square feet and are all 2-stories. The dwellings offer stainless steel appliances, hard countertops, custom cabinetry, plank flooring, walk-in closets, ceiling fans and in-suite washer and dryer.

The property is conveniently located close to Intel’s Chandler Campus and the high-tech Price Road Corridor. It is in proximity to parks, retail, freeways and major employers. It’s location adjacent to the 31.75 acre Pima Park offers an additional recreational amenity for residents.
Triple Net Events Space:
Baltimore

Exclusive events space in the heart of downtown Baltimore.

The subject property is located along the west side Guilford Ave, which is a densely developed retail and commercially-oriented corridor. Numerous shopping centers and freestanding retail uses are located along this corridor.

CAP Rate: 10% Valued at $4.6 MM

NNN Lease until 2032 with 3% annual increases and $25k/month starting rent

NOI: $466,182

Walgreens Guaranteed
Lease

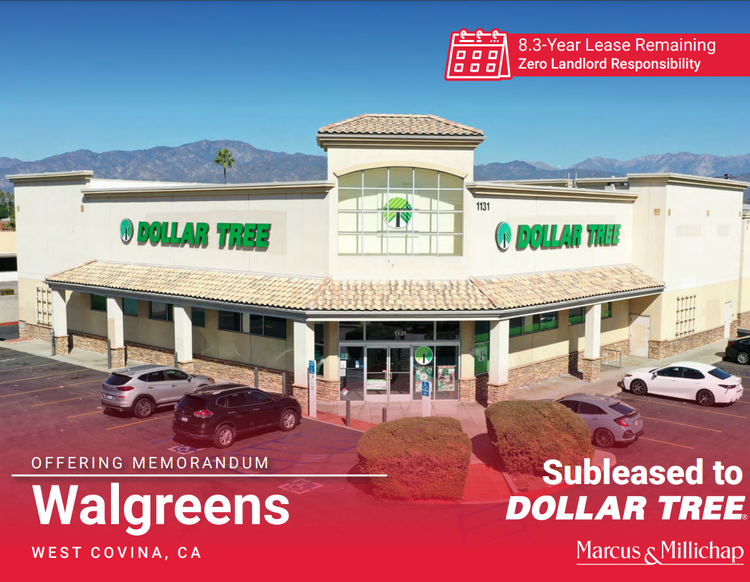
This is a 13,170 SF Single Tenant Net Leased commercial property located in the city of West Covina, CA. Situated on a signalized corner, this building offers excellent visibility and high traffic flow. This Walgreens property is currently being subleased to Dollar Tree. There are 8 years remaining on the existing Walgreens guaranteed lease with 8 years remaining. With an NOI of $435,000 and a list price of $5,612,903, this deal is being offered at a 7.75% cap rate.

– NOI: $435,000

Whataburger Ground Lease
Offering Price: $2.71M

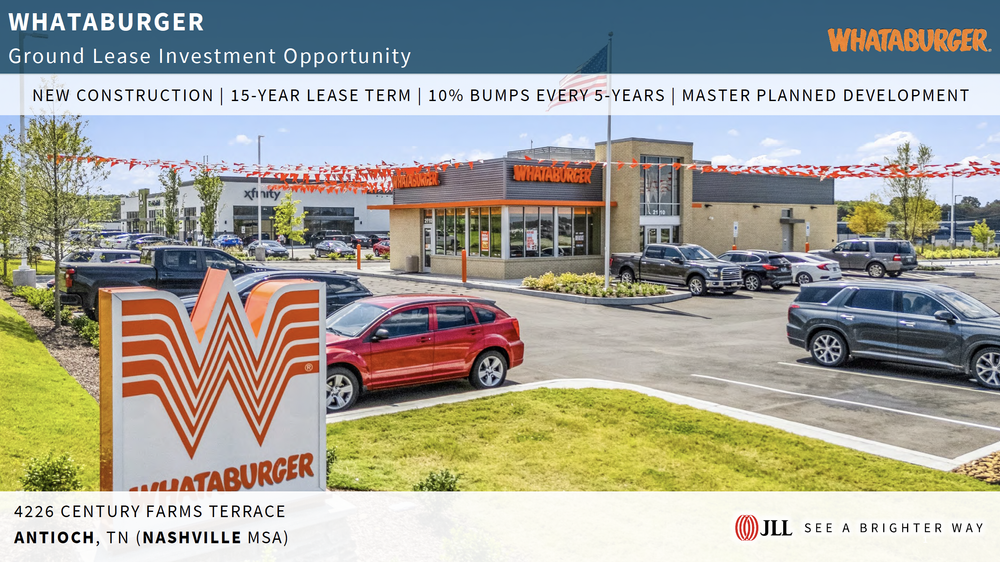
Jones Lang LaSalle Americas, Inc. (“JLL”), is pleased to exclusively offer for sale the ground lease interest in the single-tenant Whataburger (the “Property” or “Asset”) located at 4226 Century Farms Terrace in Antioch, TN.

The 15-year ground lease operates under an absolute NNN lease structure and is subject to 10% rent increases every 5-years, providing investors a hedge against inflation.

Industrial Building
on 6 Acres

Property Highlights
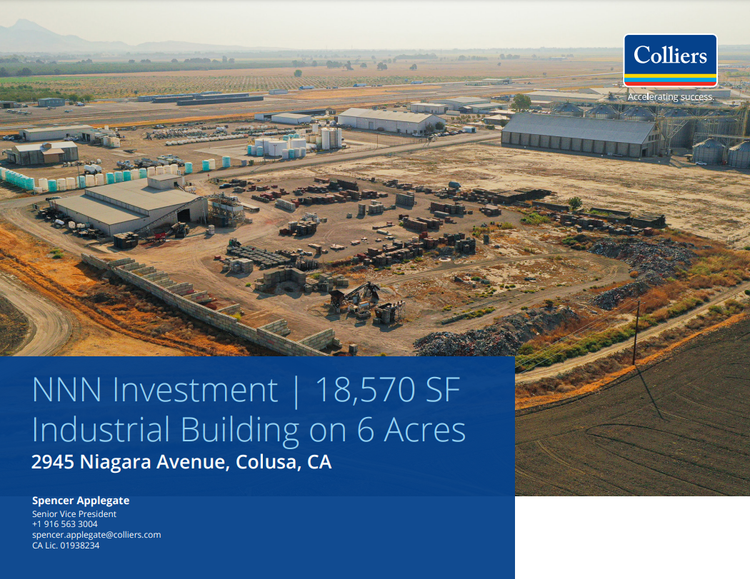
– 6 acres
– 1,200 SF office
– 540 SF breakroom
– 18,750 SF warehouse
– All weather site
– Zoning: M2 industrial
– Cannabis ready
– 1,000 amps electrical service

Location Highlights
– Located in Colusa Industrial Park
– Just east of Highway 20
– Close proximity to Colusa County Airport
– 1 hour from Sacramento

San Diego Pep Boys

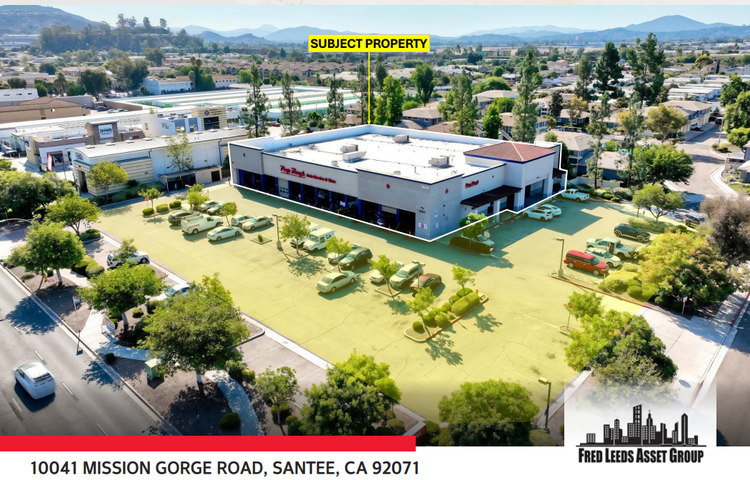
Absolute NNN ground lease.

Great real estate – 1.7 acres on Mission Gorge Rd, across from Walmart, Costco, Target, Home Depot, Trader Joe’s, and other major retailers
Current rent $175k annually, well below market with significant upside
Tenant has exercised renewal through 2033, with options extending to 2048.

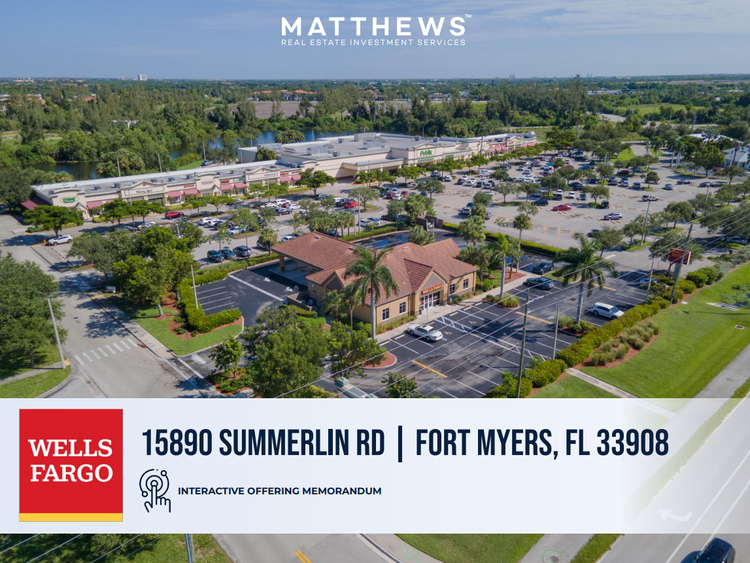
Wells Fargo –
Fort Myers

Absolute NNN Wells Fargo in Fort Myers, FL. The tenant recently exercised an option period early, and the site benefits from strong real estate fundamentals, located on a hard, signalized corner out parceled to a Publix anchored center.

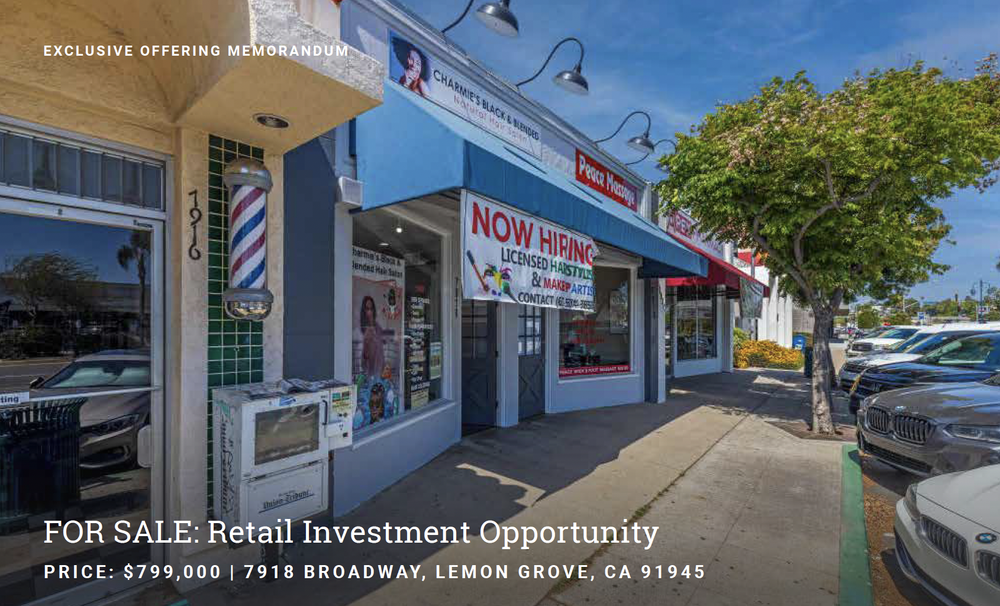
Retail Investment Opportunity | Lemon Grove, CA | Offering Price: $800k

Rare Opportunity to Acquire Multi-Tenant Retail Building Fully Renovated.

Behind the building is a huge free parking lot with 96 spaces that can be accessed via the back entrance.

The building is 2 doors down from the new CityMark development, Kelvin, which features 66 luxury apartments creating a built-in upscale customer base.

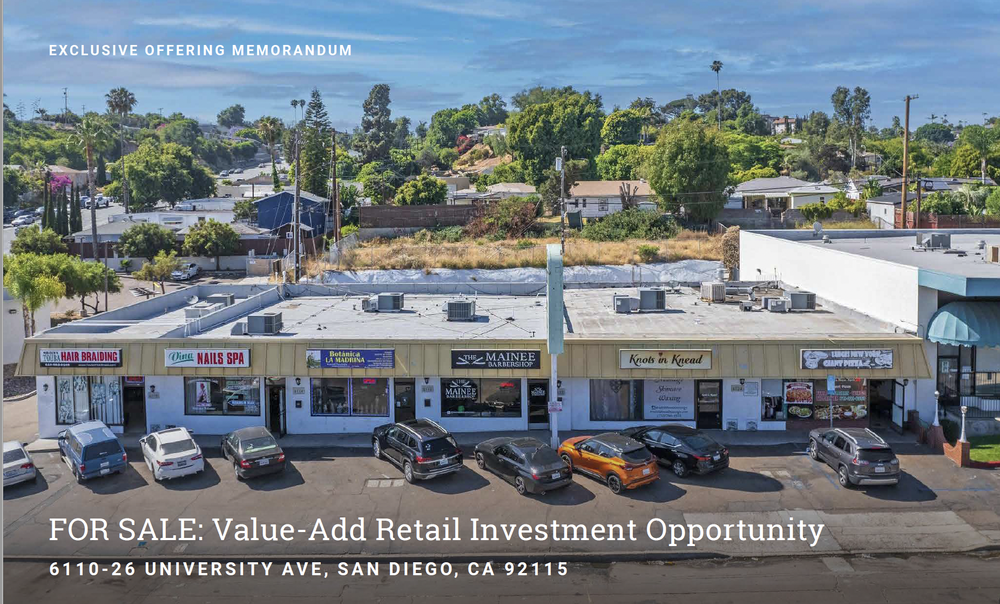
Value Add Retail | San Diego
Offering Price: $2.75M

Rare Opportunity to Acquire Multi-Tenant Retail Building Off the Corner of Busy University and College Ave.

The property is located 1 mile from San Diego State University with a student and faculty population of ±40,000.

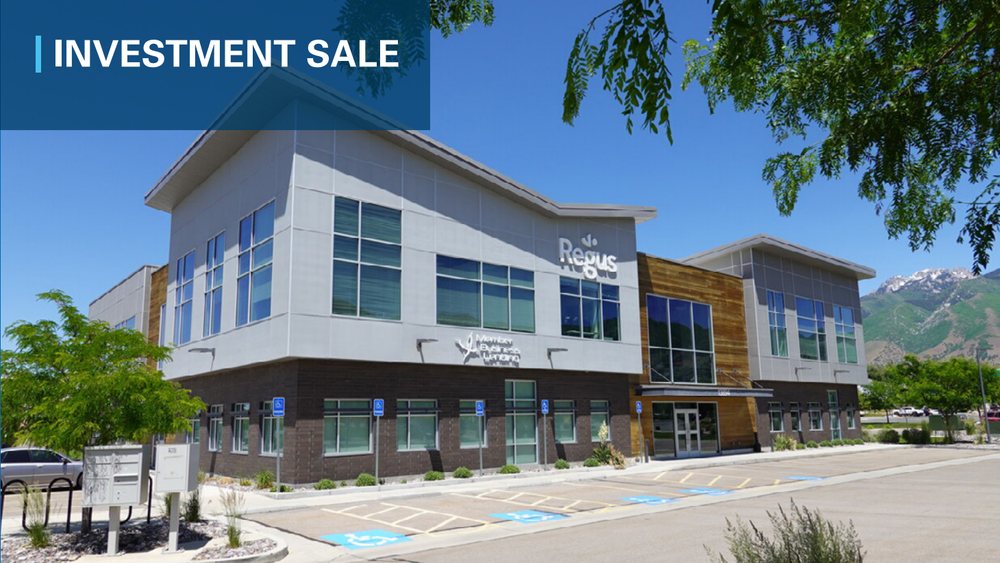
Parkway Crossing Office Building in Utah 
Offering Price: $7.9M

– Cap rate: 7.57 %
– Building size: 24,492 SF
– 100% leased (weighted average lease term 3.1 years)
– Anchor tenant is a publicly traded company Regus (NASDAQ: IWGFF)
– Three (3) tenants
– Year built: 2017
– Great parking ratio at 4.5/1,000 SF
– Ideal south valley location in a high growth market for office, retail and housing
– Adjusted NOI: $597,923 (includes 5% VMR)

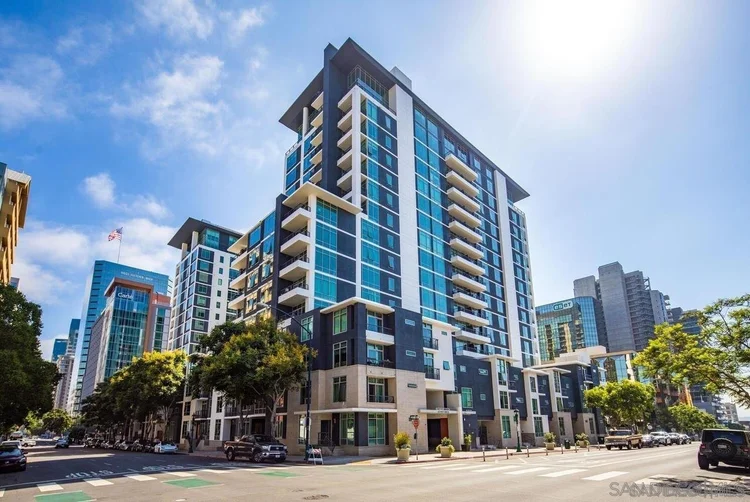
Downtown Little
Italy Condo

A ground-up development project for PondView RV Resort, 604 Golden Rd, Tifton, GA, a premium 120-site outdoor hospitality destination on 22 acres in Tifton, Georgia. Given your expertise in ground-up RV resort funding, I believe this $6.0 million project is a strong candidate for your program.

The project is strategically located at a primary transit node of the I-75 corridor, specifically designed to capture the heavy “Snowbird” migratory traffic and regional tourism. We have substantially de-risked the development phase by securing a parcel already approved for RV park use with municipal water and sewer available at the boundary.

Capital Stack: $5.4M SBA/ Conventional financing with $600k in land equity (10% injection)

Stabilized NOI: $679,779 (Year 5), providing a projected 1.48x DSCR

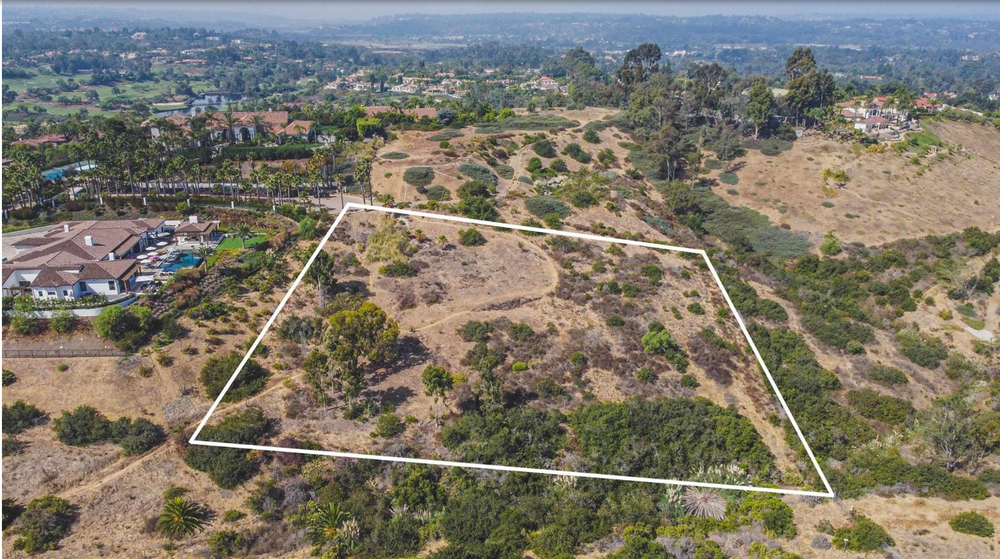
Spyglass Lot 
Offering Price: $1.6M

Breathtaking Views in Exclusive Spyglass Estates. This rare 2.74-acre lot in the prestigious Spyglass Estates offers a unique opportunity to build your custom dream home or develop a finished pad in Rancho Santa Fe.

As one of the last remaining lots in this exclusive enclave, the property is ideally located at the end of a quiet cul-de-sac, providing unmatched privacy and sweeping mountain and hillside views.

Preliminary designs have already been completed for a luxurious estate, featuring a guest house, pool, spa, and expansive outdoor living spaces. With a water lateral onsite and sewer line access, the lot is ready for your vision to come to life.

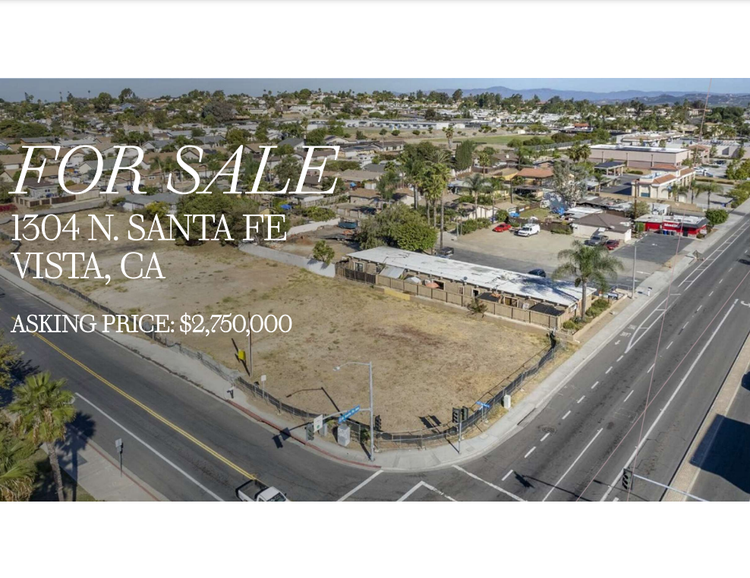
Entitled Vacant Land Vista,
CA Offering price: $2.7M

Multifamily development land located in a vibrant, walkable community minutes from downtown Vista!

– Entitlements for 36 Market Rate units.

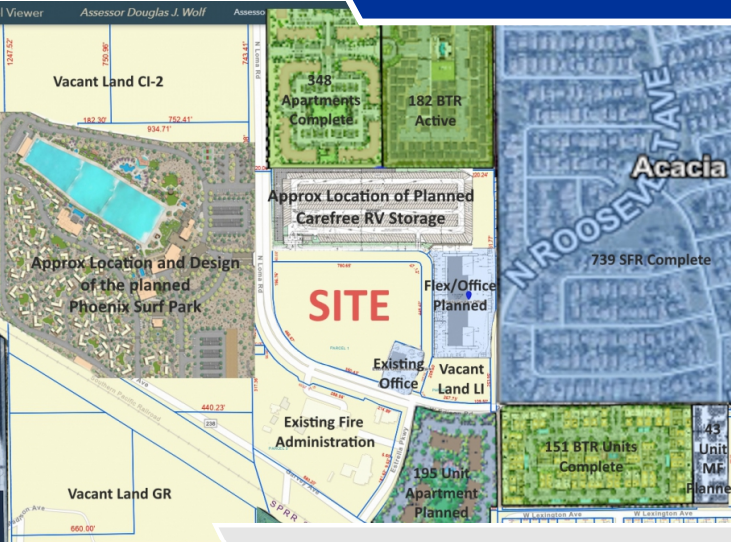
Estrella Gin Business
Park Light Industrial

Approx 9.75 acres at the Estrella Gin Business Park zoned Light Industrial with potential uses ranging from Retail and Office to Hotel and Light Industrial. The Phoenix Surf Park is scheduled to break ground in summer of 2024 , across Loma to the West.

Over 900 acres of mixed use developments underway within a mile of the Estrella Gin Business Park and Phoenix Surf Park. Within a stones throw of the property there are around 900 multifamily or build to rent units planned with around 500 units already complete or under construction.

The city itself continues to attract new retail, housing, and commercial developments on a regular basis. Owner/Agent.

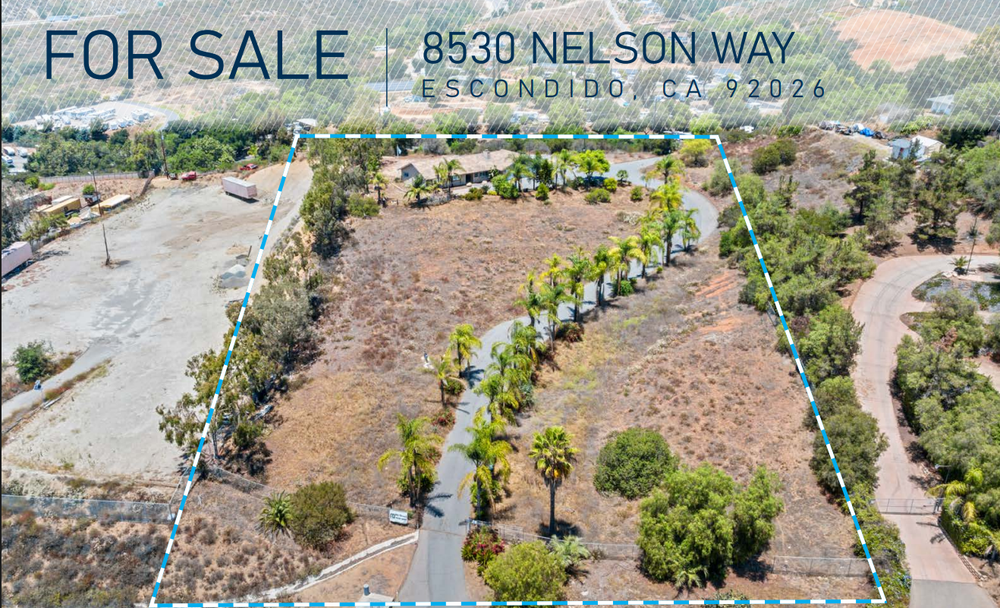
2,269sf office on 2.5 Ac Rare Escondido
Ca Industrial land

2,269sf office on 2.5 acres of rare industrial land in the outskirts of Escondido CA….

2.5 Ac Rare Escondido
Ca Industrial land

2.5 acres of rare industrial land in the outskirts of Escondido CA.

Zoning is County and more flexible than city, M-52.

Location is close to the 15 freeway entrances and exits.

8490 Nelson Way and 8530 Nelson Way can be sold together or separate.

86 acres of Prime commercial land near Old Town – Temecula CAst Item

86 ac square shaped parcel for sale, near Old Town Temecula.

Zoning is Service Commercial (SC) which allows a wide array of uses and developments.

You’ve got questions,
We’ve got answers

We believe clarity builds confidence. Here are answers to some of the most common questions we receive from sponsors, fund managers, and investors navigating private offerings.

Still have questions?

Get in touch with us today!

A 1031 exchange (also known as a like-kind exchange) is a transaction that allows a taxpayer to defer the capital gains tax that would be due on a sale of an asset. 1031 exchanges are almost exclusively used in real estate, but they can be used for other types of assets as well. A 1031 exchange allows real estate investors to defer the capital gains tax on the sale of appreciated property if they reinvest the proceeds in a new property. But while a 1031 exchange may sound simple in premise, there are specific rules that must be followed to completely defer the capital gains tax.

1921 – The Revenue Act of 1921 introduced the predecessor to the current form of tax-deferred like-kind exchange; this Act produced Section 202(c) of the IRC and allowed non-like-kind property and securities to be exchanged by investors; the exception was in cases of properties that had what is referred to as a “readily realizable market value.” However, this aspect of the Revenue Act of 1921 was later overwritten and modified by the Revenue Act of 1924, and after that the Revenue Act of 1928; the Board of Tax Appeals approved the creation of tax-deferred like-kind exchanges in 1935, adding aspects such as Qualified Intermediaries; the previously-established “cash in lieu of” clause was retained so that tax-deferred like-kind exchange transactions would not be affected.

1970 – The STARKER family sold their timber land in the Pacific Northwest to Weyerhauser Company. When they sold the property they crafted a trust agreement wherein the EXCHANGE PROCEEDS would be held by the buyer, Weyerhauser, in a separate bank account. The terms of the trust provided that Weyerhauser would use the funds to purchase REPLACMENT PROPERTY for the Starker family and for no other purpose. The trust agreement limited the Starker family access to the funds except for the purpose of buying replacement property. When the IRS saw this, it denied 1031 tax deferral to the Starker family. The IRS argued that 1031 exchange meant the swap of property between two parties. The IRS could see that if property could be sold to one person and bought from another, in a 1031 exchange, then the application of the law would become much more wide spread. Since the job of the IRS is to raise taxes it fought hard against the Starker’s trust arrangement. In a monumental and far reaching decision the tax court ruled in favor of the Starker family and against the IRS. To this day, in a tribute to this family, 1031 exchanges are often still called “Starker Exchanges.”

1984 – The outcome of the Starker Family case created the need for regulations in the industry over future delayed tax-deferred like-kind exchanges; as a part of the Deficit Reduction Act of 1984, the U.S. government added the 45 calendar day Identification Deadline and the 180 calendar day Exchange Period, creating the rules that currently govern modern delayed tax-deferred like-kind exchanges.

1031 Exchange

Section 1031 of the Internal Revenue Code allows you to exchange real or personal property that was used for rental, investment, trade, or business for like-kind real or personal property that was used for rental, investment, trade, or business to defer your capital gain, ordinary income, and depreciation recapture taxes.

1033 Exchange

Section 1033 of the Internal Revenue Code covers various forms of involuntary conversion of taxpayer property. Conversions occurs when property is destroyed, stolen, condemned or disposed of under threat of condemnation and the taxpayer receives other property or money in payment (e.g., insurance proceeds or a condemnation award).

121 Exclusion

Section 121 of the Internal Revenue Code allows homeowners who have resided in their residence for at least two of the last five years a tax exclusion. Single taxpayers are entitled to a $250,000 exclusion and married taxpayers filing jointly are entitled to a $500,000 exclusion. An exclusion allows you to have a gain on the sale of your primary residence up to the maximum limit without having to pay capital gain taxes. Any gain over and above these exclusion limits is taxable.

721 Exchange

Section 721 of the Internal Revenue Code allows you to exchange investment real estate for an interest in a Real Estate Investment Trust (REIT).

Forward 1031 Exchange

Whether you choose a simultaneous or delayed forward exchange, both have the same steps to complete. Upon selling your asset (relinquished property), you have 45 days to identify what asset (replacements property) you will be acquiring. Upon completion of the 45 days, you will have an additional 135 days to close escrow on the replacement property. The total transaction cannot exceed 180 days from the close of escrow on your relinquished property.

Reverse 1031 Exchange

As its name states, a Reverse 1031 Exchange is where you acquire an asset (replacement property) first, then have 45 days to identify what asset (relinquished property) you will be selling. You will then have an additional 135 days to complete the sale of your relinquished property. Upon the close of escrow, you can either pay yourself back for the acquisition, or payoff the loan used to acquire the replacement property prior to the selling of the relinquished property. To complete a Reverse 1031 Exchange, the taxpayer must “park” title to either the relinquished or replacement property with an Exchange Accommodation Title Holder (E.A.T). As your 1031 Exchange Accommodator, we generally act as the E.A.T.

Build to Suit or Improvement 1031 Exchange

A Build to Suit or Improvement exchange occurs when the Taxpayer wishes to make improvements to the replacement property utilizing the sale proceeds of the relinquished property. This type of exchange also requires an E.A.T. during the improvements. The improvements must be identified within the 45-Day Identification Period and title of the improved property must be passed to the Taxpayer within the 180-Day Exchange Period. When dealing with real estate, it is not necessary for the improvements to be 100% complete prior to title being acquired by the taxpayer. If the value of the improved property has been increased to an amount equal or greater than the value of the relinquished property, title may be conveyed to the taxpayer. However, the conveyed property must be substantially the same property that was identified.

In order to qualify for a 1031 Exchange, the Relinquished and the Replacement Properties must both have been acquired and “held for” investment or for use in a trade or business. The amount of time that the property must be “held for” use in a trade or business is not specified in either the Code or the Regulations.

The position of the IRS has been that if a taxpayer’s property was acquired immediately before an exchange, or if the Replacement Property is disposed of immediately after an exchange, it was not held for the required purpose and the “held for” requirement was not met.

There is no safe harbor holding period for complying with the “held for” requirement. The IRS interprets compliance based on their view of the taxpayer’s intent. Intent is demonstrated by facts and circumstances surrounding the taxpayer’s acquisition of ownership of the property and what the taxpayer does with the property. The courts have been more liberal than the IRS on these issues.

Here are some examples of transactions that should be considered to have potential for a finding by the IRS that the “held for” requirement has not been met:

The taxpayer acquires Replacement Property and immediately lists the property for sale. The IRS will interpret the intent to acquire the property for resale instead of for investment purposes.

The taxpayer receives the Relinquished Property by deed from a partnership and immediately proceeds to sell/exchange it (aka “drop and swap”).

The taxpayer acquires Replacement Property and immediately converts the property to a personal residence.

The taxpayer acquires Replacement Property and immediately transfers the property to a corporation, partnership or LLC.

Like-kind Property

The following types of property generally WILL qualify as like-kind property:

Single-family residences
Multi-family residences
Commercial office space
Retail shopping centers or strip malls
Industrial warehouses
Vacant or undeveloped land
Oil and gas interests
Mineral rights
Water rights
Tenant-in-common (TIC) property interests
Delaware Statutory Trust (DST) property interest
Vacation rentals

Non-like-kind Property

The following types of property will generally NOT qualify as like-kind property:

Personal use assets
Primary residences
Second homes
Vacation homes (personal use)
Property held for sale
Property held for development
Property acquired for conversion, then sold
Property acquired to fix-up and sell
Securities
Cash
Stocks
Bonds
Mutual funds
Interests in an Entity
Partnership interests owned in a general or limited partnership
Membership interests held in a limited liability company (unless it is a single-member LLC)
Shares of stock in a corporation

Foreign Property

As a result of the Revenue Reconciliation Act of 1989, real property located within the United States and real property located outside of the United States are no longer of like-kind. However, foreign property may still be exchanged for other foreign property. Section 7701 defines the borders of the United States as all fifty states and the District of Columbia. For purposes of the 1031 code, the Internal Revenue Service defined the borders of the U.S. to include the U.S. Virgin Islands given the Exchanger is: (1) A citizen or resident of the United States and (2) Has income derived from sources within the U.S. Virgin Islands, is effectively connected to the performance of a trade or business in the U.S. Virgin Island or files a joint return with an individual who derives an income or is connected to a trade or business within the U.S. Virgin Islands. Both requirements must be satisfied to exchange real property in the fifty states and real property located in the U.S. Virgin Islands. Puerto Rico is not eligible for 1031 eligibility while real property located in Guam is eligible.

Vacation/Second Homes

Revenue Procedure 2008-16 provides specific safe harbor language that clarifies when your vacation home, second home or primary residence that was converted to investment property would be considered as “qualified use property” and therefore qualify for 1031 Exchange treatment pursuant to Section 1031 of the Internal Revenue Code, although a safe strategy is to convert the second home into an investment property and rent out the property at fair market value for two years prior to the sale and exchange of the property. Alternatively, the owner could rent out their second home for a minimum of 14 days at fair market value and limit their own personal use to 14 days per year for the two years prior to the sale of the property or 10 percent of the number of days that the property is rented at fair market value during each year.

The IRS has very specific definitions regarding personal use if for any part of a day the property is utilized by the owner. This includes the owner who has an interest in the second home or vacation property as a tenant-in-common interest. Furthermore, use by any member of the owner’s family counts as personal use days unless the second home or vacation property is rented out to those family members as a full time principal residence at a fair market rent.

Another IRS requirement specifies that if the owner rents out the vacation or second home property at less than fair market value, the days rented will be considered personal use days. Lastly, an additional rule defines that any use by the owner who uses the property under an arrangement which enables them to use some other property is considered personal use. With so many intricate IRS rules regarding vacation and second home properties, always check with your tax advisor.

The successful completion of a 1031 Exchange transaction requires you to comply with certain 1031 Exchange deadlines pursuant to Section 1031 of the Internal Revenue Code. The 1031 Exchange deadlines consist of the 45 calendar day identification deadline and the 180 calendar day 1031 Exchange completion period. These 1031 Exchange due dates cannot be extended, unless the President of the United States declares a natural disaster area that affects the properties or parties involved with the 1031 Exchange transaction.

45 Calendar Day Identification Deadline

When completing a 1031 Exchange transaction you must identify your potential like-kind replacement properties to your Qualified Intermediary no later than midnight of the 45th calendar day following the close of the relinquished property sale transaction. Holidays and weekends count. The formal identification should be made in writing to your Qualified Intermediary via email, facsimile, U.S. Mail, or overnight courier. You can change your mind by formally revoking the identification of your like-kind replacement properties and subsequently submit a new identification form at any time during your 45 calendar day identification period, but you cannot change your mind after the 45 calendar day identification period has expired. Revoking and submitting a new identification form does not change or reset the original 45 calendar day identification deadline.

Failure to identify like-kind replacement properties within the 45-calendar day window will result in a failed 1031 Exchange transaction and the transaction becomes a taxable sale.

180 Calendar Day Exchange Period

You must complete your 1031 Exchange transaction, which includes the conveyance (receipt) of title to all of your like-kind replacement properties that you intend to acquire, no later than the earlier of:

Midnight of the 180th calendar day following the close of the relinquished property sale transaction,

Or

2.) The due date of your Federal income tax return for the tax year in which the relinquished property was sold, including any extensions of time to file.

You do not need to be concerned about part (2) above unless the first relinquished property transaction sold and closed on or after October 17th and on or before December 31st of any given tax year, which would mean that the 180th calendar day would fall after April 15.

You will have less than 180 calendar days to complete your 1031 Exchange transaction if you have a 1031 Exchange transaction closing on or after October 17th and on or before December 31th of any given income tax year, unless you file for an extension of time to file your federal and, if necessary, state income tax returns. Once the extensions of time have been filed, you must complete your 1031 Exchange transaction within the 180 calendar days before you actually file your Federal and, if applicable, state income tax returns.

The 45-Day Rule for Identification imposes limitations on the number of potential Replacement Properties, which can be identified and received as Replacement Properties. More than one potential Replacement Property can be identified by one of the following three rules:

Three Property Rule

You can identify up to 3 separate properties regardless of their fair market value. This is the rule most commonly used.

200% Rule

You can identify as many properties as you prefer as long as the aggregate fair market value of the replacement properties does not exceed 200% of the aggregate fair market value of all of the exchanged properties as of the initial transfer date. This rule is often used in exchanges where the taxpayer is selling one large asset or multiple assets and acquiring more than 3 assets. As an example if a taxpayer were to sell a property for 1 million dollars he/she could identify up to 2 million dollars in properties, regardless of how many properties that amount consisted of.

95% Rule

This rule allows you to identify any number of replacement properties at any value, but the fair market value of the properties acquired by the end of the 180 days must be at least 95% of the aggregate fair market value of all the potential replacement properties identified. This rule is used for large portfolio sales. It isn’t very common, and can be risky.

Grow Your Real Estate Wealth Faster

A 1031 Exchange is a wealth building tool, not just a tax code. Investors who are well advised use this strategy to keep their wealth in their family. The concept is to exchange throughout your life, creating and keeping the wealth throughout one’s life. When you pass away, your family inherits the assets, and a full step up in basis occurs. This means your family will inherit these assets and the tax liabilities are removed. A 1031 exchange is like a 401k for property — but you don’t have to wait until you’re 70 to enjoy your wealth!

The person who helps you with a 1031 exchange is referred to by the tax code as a “qualified intermediary,” also commonly referred to as an exchange facilitator or intermediary. A “qualified intermediary” is basically a middle-man who facilitates the transaction. “Qualified” does not refer to education or experience, so you have to be careful who you use. Don’t settle for a bargain-basement facilitator who will simply fill out the forms. You’ll save more and rest easier with the help of a highly experienced facilitator.

For Your Peace of Mind, Choose a Qualified Intermediary Who:

Has Completed Thousands of 1031 Transactions: no two transactions are alike, some are very complex. Your Investors 1031 Exchange Facilitator can advise you on the best way to structure your transaction to meet your investment objectives and for the best possible tax advantages.

Is An Expert in These Sections of the Internal Tax Code: Your Investors 1031 Exchange Facilitator spends 20-30 hours every year staying up to date so that you can be rest assured that you are being properly advised on your strategy. The tax code is silent in many key areas. Your Investors 1031 Exchange Facilitator can point out the grey areas you may be exposed to so you can decide how you want to structure the transaction.

Can Stand up to the Scrutiny of the IRS: Investors 1031 Exchange has completed thousands of 1031 Exchange transactions with a flawless track record with regard to Internal Revenue Service audits.